

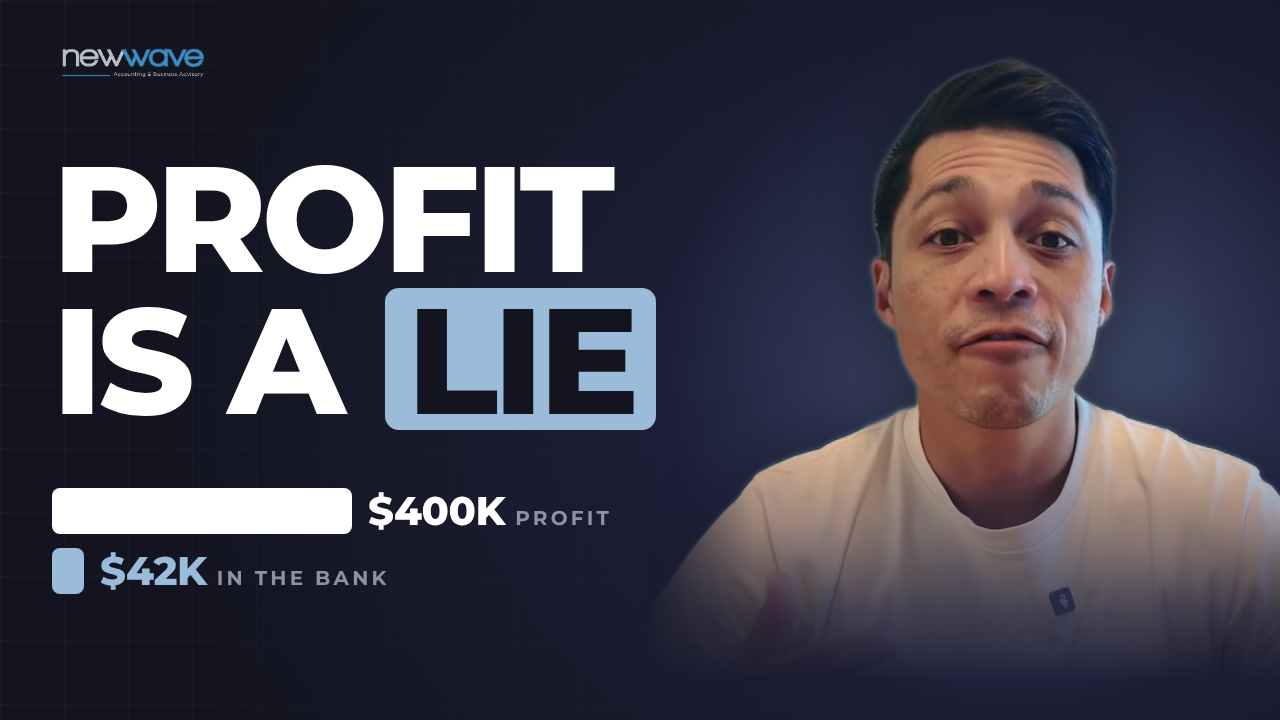
Profitable but no cash in the bank? You’re not alone, and it rarely means your accounts are wrong. Hypothetically, your profit and loss says you made $400,000 this year and your bank account says $42,000. Both numbers can be true at the same time, and the gap between them is the number one reason good, busy, profitable businesses run out of cash.
The reason is timing. Your profit and loss is a story about performance, while your bank account is a story about when money moves. Cash almost always leaves through the same five places, and the fix for all of them is the same: separate the money before it feels like yours.
In Episode 21 of Business Uncut, Reuben walks through where profit and cash separate, the five leaks ranked by how often they’re the culprit, the new Payday Super timing rule, the three traps that make it worse and one 20 minute action to take this week.
Key takeaways
- Profit measures performance. Your bank balance reflects timing. Both can be true at once.
- Cash usually leaks through five places: tax you haven’t paid, stock and work in progress, debtors, loan principal and assets, and drawings.
- Since 1 July 2026, Payday Super means super has to reach the fund within seven business days of payday.
- The fix for all five: separate the money before it feels like yours, starting with a Tax and Super account this week.
Watch the full episode on the New Wave YouTube channel.
Why profit and cash tell two different stories
Profit says “you earned it”. Cash says “you’ve got it”. The two are related, but they aren’t the same thing, and your profit and loss ignores a whole pile of real money movements.
None of the following shows up as an expense, yet every one of them empties the account:
- Stock sitting in your warehouse
- Money your customers haven’t paid you yet
- The principal on your loans
- Assets you bought outright, like the new ute
- Tax you owe but haven’t handed over
- Money you’ve taken out as drawings
A hypothetical example: $400,000 of profit and a tighter account
Here’s a hypothetical. You run an ecommerce brand on the Gold Coast turning over $3 million, and your accounts show a net profit of $400,000. Over the same year:
Hypothetical example
Same year, same business. The gap is timing, not a broken set of accounts.
- You tip an extra $180,000 into stock because supply gets unreliable and you panic buy
- You pay down $100,000 of loan principal
- You put aside nothing for tax, and the bill is sitting there waiting
- You draw out what feels reasonable along the way
The result: $400,000 of profit, and somehow the account is tighter than it was in January. That isn’t a profit problem, and it isn’t really a discipline problem either. It’s a timing problem that nobody mapped.
Timing problems are fixable, as long as you can see them. Below are the five places cash hides, ranked by how often they’re the culprit, so work through them in order.
Leak 1 Tax you’ve already earned but haven’t paid
This is the big one, and it’s the leak that ruins the most good businesses. Profit creates a tax liability the moment you earn it, not the moment the bill arrives. There’s often a long gap between the two, and in that gap the money feels like yours.
Hypothetically, you have a strong year, spend like it’s all yours, and then a lodgement and an instalment land in the same quarter. The principle: tax isn’t a bill, it’s a withholding. It was never your money.
Leak 2 Stock and work in progress
Every dollar of stock on your shelf is a dollar of cash converted into cardboard. For builders, work in progress works the same way: it’s work you’ve done but haven’t invoiced yet.
Hypothetically, if you lift stock holdings by $180,000 across a year, that’s $180,000 of cash gone, and your profit and loss shows nothing. Stock is cash wearing a costume.
Leak 3 Debtors
Debtors are simply the money your customers owe you, and it’s entirely possible to invoice yourself to insolvency. Revenue is recognised when you invoice, cash arrives when they pay, and you fund the distance between those two dates.
Hypothetically, if you turn over $3 million and your average collection time slides from 30 days to 60, you’ve quietly lent your customer base around $250,000, interest free. Your payment terms are a loan you never agreed to make.
Leak 4 Loan principal and assets
When you repay a loan, only the interest hits your profit and loss. The principal just leaves. Equipment is similar: you might get a deduction over time through depreciation (spreading the cost over the asset’s life), but the cash left in one hit.
With the cash rate sitting at 4.60% after the rise on 29 September, repayments are biting harder than they did a couple of years ago. The bank takes cash, and your accounts only show interest.
Leak 5 Drawings, dividends and the owner’s lifestyle
This is the awkward one. Money you take out as an owner usually isn’t a wage expense, so it doesn’t reduce profit, but it absolutely reduces the balance.
Hypothetically, two directors each take out a bit extra across the year with no payroll record of it, and at year end everyone is surprised. If you don’t set your own pay deliberately, the business sets it for you, and it always sets it too high.
Profit is a story about performance. Cash is a story about timing.
Payday Super: a timing change, not a leak
There’s a sixth item, and it’s new. From 1 July 2026, super has to reach the employee’s fund within seven business days of payday, and there’s a redesigned super guarantee charge if it doesn’t.
If you were quietly using quarterly super as a cash buffer, that buffer is gone. It was never really a buffer anyway: it was a loan from your staff.
So that’s five leaks and one new rule. The fix for all of them is the same: separate the money before you feel like it’s yours.
Three traps that make a cash problem worse
We see the same three mistakes again and again:
- Using your bank balance as your scoreboard. It’s a lagging number, polluted by tax you owe and bills you haven’t paid, and it tells you nothing about next month.
- Fixing a cash problem with a debt product. Overdrafts and invoice finance are genuine tools, but if the leak is a 60 day collection cycle, borrowing just makes the leak more expensive. Fix the plumbing first.
- Waiting for year end to find out. By the time the accounts are done, you’re looking at a photograph of something that already happened. It’s the most expensive habit in small business.
Your one action this week
This week
This takes about 20 minutes and needs no spreadsheet heroics:
- Open a second bank account and call it Tax and Super.
- Set a standing transfer out of every deposit. Pick the percentage with your accountant so it suits your structure, your profit and your instalments.
- While you’re in there, pull your debtors list and ring the oldest three.
Separate the money, then chase the money. Do it Tuesday morning and you’ll feel different by Friday.
Frequently asked questions
Why is my business profitable but I have no cash?
Because profit measures performance and your bank balance reflects timing. Your profit and loss doesn’t show money tied up in stock, unpaid customer invoices, loan principal, assets bought outright, tax you owe but haven’t paid, or owner drawings, yet all of them reduce your cash.
Do loan repayments show up in profit and loss?
Only the interest does. The principal leaves your account without appearing as an expense, which is why a business can look healthy on paper while repayments drain its cash.
How much should I set aside for tax from each deposit?
There’s no single percentage that suits every business. Agree a figure with your accountant based on your structure, your profit and your instalments, then set a standing transfer into a separate Tax and Super account so the money never feels like yours.
What does Payday Super mean for my cash flow?
From 1 July 2026, super has to reach the employee’s fund within seven business days of payday, with a redesigned super guarantee charge if it doesn’t. If you relied on paying super quarterly as a cash buffer, that buffer is gone, so set super aside as you go, alongside your tax.
Keep reading
Can’t find your profit in the bank?
Our team will map your cash cycle properly and show you exactly where the gap is.
General information only, not personal tax, legal or financial advice. Figures are hypothetical examples. Talk to your adviser about your own situation.


