

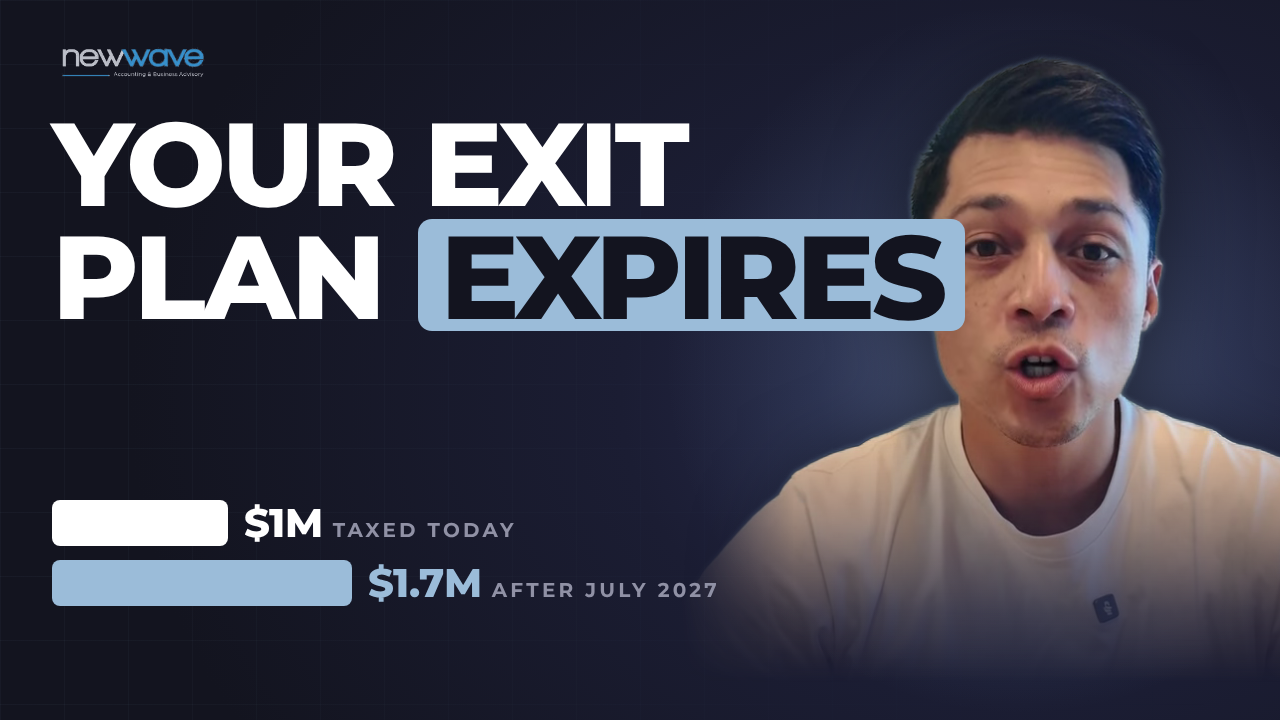
CGT changes 2027, in one line: from 1 July 2027, the 50% capital gains tax discount is gone for most owners, and it’s already law. If your exit plan quietly assumes you’ll only pay tax on half your gain when you sell, that plan now has an expiry date.
Our view: don’t sell your business just to beat a tax deadline. But if a sale was already on the cards and you’re not covered by the small business concessions, run the numbers now. Some owners need to act. Others are completely safe.
In Episode 25 of Business Uncut, Reuben walks through what the new law changes, four checks to work out where you sit, and the traps that catch owners out.
Key takeaways
- From 1 July 2027 the 50% CGT discount is replaced for most owners by indexation and a 30% minimum tax on gains. It’s already law.
- On an asset that grows faster than inflation, like a good business, the taxable gain can nearly double.
- The small business CGT concessions survived the change, and companies and new residential dwellings are treated differently.
- Don’t sell just to beat the deadline. Run the four checks first.
What’s changing on 1 July 2027
In June, Parliament passed the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, and it received Royal Assent on 26 June. This is no longer a Budget idea floating around. It’s law.
Capital gains tax is the tax you pay on the profit when you sell something that has gone up in value: a business, a property, a parcel of shares. For decades, individuals, trusts and partnerships that held an asset for more than a year only paid tax on half the gain. That’s the 50% discount, and plenty of owners have built their retirement around it without ever saying so out loud.
From 1 July 2027, that discount is replaced by two things:
- Indexation: your original purchase price is increased for inflation before the gain is worked out.
- A new floor: a 30% minimum tax on gains.
Indexation sounds fair, and in a high inflation stretch it does help. The catch is growth. When an asset has grown much faster than inflation, which is exactly what a good business does, the inflation adjustment is small and the taxable gain is big.
A hypothetical example: the same $3M sale, before and after
Here’s a hypothetical, kept simple by ignoring the transition rules for now. You bought into your business for $1M ten years ago and you sell it for $3M after the deadline. That’s a $2M gain.
Hypothetical example
Bought for $1M, sold for $3M after the deadline: a $2M gain. Ignores the transition rules.
- Old rules: half the gain is taxed, so $1M lands on your return.
- New rules: say indexation lifts your cost base (basically what you paid) by $300K. Now $1.7M is taxable.
Same sale. Same business. Nearly double the taxable amount.
Should you sell before the deadline?
Before anyone lists the business on Monday: plenty of owners are protected. The ones who should be running the numbers now already had a sale on the cards for the next couple of years and aren’t covered by the small business concessions. These four checks will tell you whether 1 July 2027 is your problem or just someone else’s headline.
A tax deadline is a terrible negotiating position.
Check 1 Do the small business concessions protect you?
The small business CGT concessions are special tax breaks for smaller businesses, and they survived the change. For a lot of owners, they can be worth even more than the discount.
To get in the door, you generally need either:
- turnover under $2M, or
- net assets (what you own minus what you owe) under $6M, counting connected businesses but not your home or your super.
The best of them is the 15 year exemption. It can make the whole gain tax free if the business has been owned for 15 years and you’re 55 or over and retiring. Hypothetically, a builder who started his business in a family trust 20 years ago, sitting just under the asset test, might already have a zero tax exit lined up.
The principle: if you qualify, there’s no rush. Protect your eligibility instead.
Check 2 Who owns the asset?
The change only bites individuals, trusts and partnerships. Companies never got the 50% discount in the first place, so a company selling an asset is no worse off on this front. New residential dwellings also keep the 50% option.
That means two owners selling similar assets can land in very different places depending on whose name is on the title. Hypothetically, a real estate agent holds an established investment unit (established meaning not brand new) in her family trust, and a new build in her own name that qualifies under the new dwelling rules. The unit is caught. The new build can still use the discount.
The principle: the structure decides the tax, not the asset.
Check 3 When does the sale count?
For most sales, the tax event happens when you sign the contract, not when it settles. A contract signed in June 2027 that settles in August is generally still under the old rules. If a buyer is already circling, the real deadline is the day the contract is signed.
Hypothetically, an ecommerce owner who had planned to sell late next year could aim to have terms agreed and the contract signed by May instead.
The principle: plan the deal backwards from the contract date, not the settlement date.
Check 4 Will the new 30% floor bite?
The 30% minimum tax means a big gain can’t be dragged down by selling in a quiet year. Plenty of owners planned to retire, drop their income to almost nothing, then sell.
Under the new rules, a hypothetical taxable gain of $1M carries at least $300K in tax, no matter how low the rest of your income is. That strategy is mostly gone.
The principle: if your plan relied on a low income year, rebuild it now.
Four traps that catch owners out
- The fire sale. Rushing a buyer to beat 1 July can knock more off your price than the tax would ever have saved. A tax deadline is a terrible negotiating position.
- Guessing your eligibility. The $6M asset test counts connected businesses and some related entities. Owners get it wrong all the time, usually in the optimistic direction.
- Ignoring the transition rules. There are transition rules tied to what your assets are worth on 1 July 2027, so don’t assume your whole gain is caught, or that none of it is. Get the detail on your assets, and consider whether a proper valuation around that date makes sense.
- Restructuring on half the picture. The 30% minimum tax on discretionary trusts (a family trust where the trustee decides who gets what each year) is still only proposed, from 1 July 2028. It’s not law. The draft is out and consultation has closed, but how it interacts with capital gains hasn’t been released yet. Don’t tear up your trust on a draft.
For more on that trust proposal, see our guide to the proposed 30% minimum tax on trust income.
Your one job this week
This week
Write a list of every asset you might sell in the next five years: the business, property, shares. Next to each one, jot down:
- who owns it
- when you bought it
- roughly what you paid
That one page is what turns this from a worry into a plan.
Frequently asked questions
When does the 50% CGT discount end?
From 1 July 2027, the 50% discount is replaced for most owners by indexation of the cost base and a 30% minimum tax on gains. It’s already law under the Treasury Laws Amendment (Tax Reform No. 1) Act 2026, which received Royal Assent on 26 June. Transition rules are tied to what your assets are worth on 1 July 2027.
Who is affected by the CGT changes in 2027?
The change bites individuals, trusts and partnerships. Companies never got the 50% discount, so a company selling an asset is no worse off on this front, and new residential dwellings keep the 50% option. Owners who qualify for the small business concessions may also be protected.
Do the small business CGT concessions still apply after 1 July 2027?
Yes, they survived the change. You generally need turnover under $2M or net assets under $6M, counting connected businesses but not your home or super. The 15 year exemption can make the whole gain tax free if the business has been owned for 15 years and you’re 55 or over and retiring.
Is CGT triggered at contract date or settlement date?
For most sales, the tax event happens when you sign the contract, not when it settles. A contract signed in June 2027 that settles in August is generally still under the old rules, so the contract date is the one to plan around.
Keep reading
Planning a sale in the next few years?
We’ll run the before and after numbers on your own exit plan, so the deadline doesn’t make the decision for you.
General information only, not personal tax, legal or financial advice. Figures are hypothetical examples. Talk to your adviser about your own situation.


